From mandate to mainstream: key takeaways on SEPA Instant as the default

Vlad Macovei
09 Oct 2026 / 10 Min Read
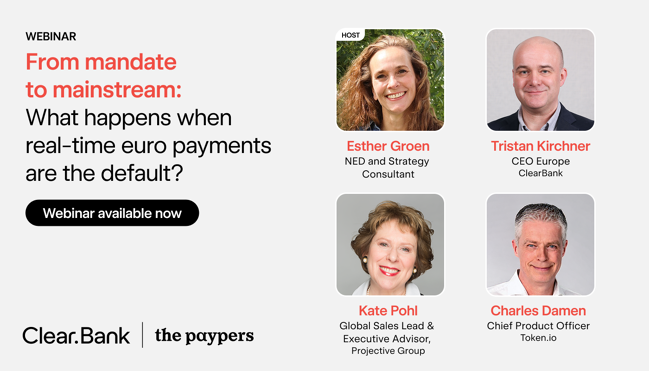
On 30 September 2026, The Paypers and ClearBank hosted the webinar 'From mandate to mainstream: What happens when real-time euro payments are the default?'. Esther Groen, NED and Strategy Consultant, moderated a panel with Tristan Kirchner, CEO Europe at ClearBank, Kate Pohl, Global Sales Lead and Executive Advisor at Projective Group, and Charles Damen, Chief Product Officer at Token.io.
The discussion looked at what changes once instant payments under the Instant Payments Regulation (IPR) become the norm. The IPR (Regulation (EU) 2024/886) required payment service providers in the euro area to receive instant euro credit transfers from 9 January 2025 and to send them from 9 October 2025, when Verification of Payee (VoP) also became mandatory. Electronic money institutions (EMIs), payment institutions (PIs) and providers outside the euro area face their deadlines in 2027.
In brief
- SEPA Instant is forecast to overtake standard SEPA Credit Transfers by 2030.
- Instant settlement lets merchants release goods at once and refund customers instantly.
- Banks must fit fraud screening and compliance checks into a 10-second execution window and keep their APIs and customer service running around the clock.
- Commercial API schemes such as SPAA and UKPI let banks earn revenue from compliance-driven APIs.
Before and after the mandate
When PSD2 required banks to open payment initiation APIs, SEPA Instant was available at only 30% to 40% of banks, Damen recalled. Most account-to-account payments therefore ran over standard SEPA Credit Transfer and settled the next day, so ‘the merchant isn't certain then that they would actually receive the funds after they have released the goods’.
With SEPA Instant now mandatory across the euro area, a merchant can confirm payment within seconds and release goods straight away. Kirchner argued that the change goes beyond compliance: ‘the market is actually choosing instant payments and it's not just complying with them’. Once instant transfers are universally available and priced the same as standard ones, customers have little reason to choose the slower rail.
Uptake since the mandate
Damen reported ‘a real uptake since the mandatory introduction of SEPA Instant’. Kirchner cited Celent research forecasting that, by 2035, an average of 75% of SEPA credit transfers will be instant, with instant volumes overtaking standard transfers by 2030. Banks are investing accordingly: 61% of those surveyed expect to spend more than EUR 20 million on compliance, including 23% who expect to spend between EUR 50 million and EUR 100 million. Most EMIs and PIs, by contrast, expect to spend less than EUR 10 million. The report, 'SEPA Instant: Build it and they will come' (January 2026), was commissioned by ClearBank and surveyed more than 100 financial institutions in 10 European markets.
What merchants and their customers gain
For merchants, refunds change too. A card refund can take a day or two, whereas an instant one is immediate, and Damen observed that ‘if you provide a consumer with an instant refund, the consumer will very likely transact again on your website to make use of those funds’.
For Pohl, consumers value payments that work around the clock, while corporates are ‘more interested in real time information than they really are in real time payments’. Outside time-critical cases such as M&A deals, ‘knowing that it's reliable, knowing that it might be same day is far more critical than having it be within 10 seconds’.
Instant payments as plumbing, and where banks add value
Kirchner described instant payments as ‘really acting like the plumbing’: universally available and reliable. The strategic question is which layer of the value chain an institution wants to own, from customer experience, payment initiation and orchestration to fraud prevention, reconciliation, liquidity management and clearing and settlement. The answer depends on size and existing tech stack, and he warned against owning every layer ‘simply because it's technically possible to do that’. Institutions should differentiate where customers see value and partner for the rest.
The same logic applies to direct scheme participation, which the IPR opens to EMIs for the first time. Damen called direct access to clearing ‘a very significant undertaking’: buying directly from the scheme may lower the cost per transaction, but ‘you have to factor in the operational elements, and that's often forgotten in the overall business case’.
Kirchner drew on the UK, where Faster Payments, launched in 2008, has run for close to 20 years. Reaching full 24/7 resilience there was ‘a multi-year build’. Direct participation suited well-resourced players, while most institutions got there through partners. Unlike the UK, a single market where Faster Payments grew organically, SEPA Instant is mandate-led and spans many jurisdictions, so the IPR compresses that journey into a few years.
Fraud and compliance checks inside a 10-second window
Pohl listed what instant readiness demands of banks: 24/7/365 operations with no downtime, a 10-second execution window in which fraud and compliance due diligence must be completed, VoP, and real-time fraud monitoring. For many banks, ‘it's a huge and costly core system upgrade’. VoP checks that the payee's name matches the IBAN before the payer authorises the transfer, so it runs before the 10-second clock starts.
Fraud is harder to contain because, unlike cards, instant payments have no chargeback. As Kirchner put it, ‘once the push payment has happened, the funds are cleared and settled, which makes the recovery mechanism extremely difficult’. With responsibility spread across several parties in the payment chain, clearer industry rules are needed for when something goes wrong. VoP helps, but works best alongside behavioural analytics, transaction monitoring and information sharing between parties.
The audience agreed: about a third of attendees named fraud and liability as their hardest strategic question, the top answer in the poll. Kirchner's advice was to start operational preparation now, even before final scheme rules are known, and to scale controls to risk, since ‘small EUR 5 p2p coffee shop transactions will not need the same controls as hotel or car rental’. Getting VoP right alongside embedded fraud monitoring could become a lasting point of differentiation: ‘that is the secret sauce’.
An audience member asked whether transaction monitoring could also move ahead of the 10-second clock, as VoP does. Pohl's reading was that it has been argued it should, but it does not sound as if it will.
Resilient APIs and round-the-clock service
Pohl also flagged resilient APIs, ‘something that banks have struggled with to some extent over the years’. Customer service is a second pressure point, because round-the-clock payments require round-the-clock support.
Commercial APIs and a return on compliance spend
Damen argued that regulation alone will not drive adoption: ‘We don't believe though that everything should be driven by regulation.’ Commercial incentives let banks earn a return on their PSD2 APIs.
In Europe, the European Payments Council's SEPA Payment Account Access (SPAA) scheme lets banks be paid for premium APIs. SPAA covers services beyond the PSD2 minimum, such as payment certainty and recurring payments. In the UK, the UK Payments Initiative (UKPI), owned by banks and third-party providers and with Damen on its board, runs commercial variable recurring payments on the same principle. UKPI launched on 2 June 2026. Germany's giroAPI scheme has also announced premium APIs.
Wero, iDEAL and the digital euro
Which payment methods to support was the second most common answer in the audience poll. Damen pointed to the Netherlands, where the move from iDEAL to Wero has raised questions for merchants about pricing and payment certainty. iDEAL gave merchants confidence that funds would arrive, and some are now weighing Wero against pay by bank or offering both. Wero, developed by the European Payments Initiative (EPI), is the pan-European scheme replacing iDEAL.
On the digital euro, Damen argued that it should work like a payment account, letting merchants initiate payments through the same APIs they use for bank accounts, with consumers deciding whether to adopt it.
Interoperability beyond Europe
Kirchner sees cross-border interoperability as the next stage, citing the Eurosystem's work to connect its TARGET Instant Payment Settlement (TIPS) service with India's Unified Payments Interface (UPI), Nexus Global Payments and Switzerland's SIC system. In November 2025, the ECB moved the TIPS-UPI link into its realisation phase. The technical connection is the easier part, he said; the harder work is agreeing which rules apply and how fraud is handled across systems.
Pohl noted that corporates and consumers care less about the route a payment takes than about timing and seamless service. She also relayed a question debated at Sibos that week: whether the BIS, SWIFT, Mastercard or fintechs will connect stablecoins, tokenised deposits, the digital euro and wallets across borders.
Advice from the panel
With Wero, the digital euro, PSD3 and legacy scheme migrations competing for the same budgets, Pohl warned that ‘waiting is absolutely the last thing you should be doing’ and urged banks to prioritise their change portfolio. Her closing advice: ‘Plan early.’ Kirchner urged organisations to be clear about where to play; as he put it earlier in the session, ‘start with the strategy, not the technology’. Groen closed by noting that ‘instant payment is no longer a compliance project’.
The full recording is available on demand.
About the author

Vlad is a Senior Writer at The Paypers, working in the commercial team. He uses his research, content, and people skills for all editorial activities revolving around payments, banking, and fintech. Vlad has a degree in Biology and Molecular Genetics and an extensive background in creative writing. You can reach out to him on LinkedIn.
About Kate Pohl
About Tristan Kirchner
About Charles Damen
About Esther Groen

The Paypers is a global hub for market insights, real-time news, expert interviews, and in-depth analyses and resources across payments, fintech, and the digital economy. We deliver reports, webinars, and commentary on key topics, including regulation, real-time payments, cross-border payments and ecommerce, digital identity, payment innovation and infrastructure, Open Banking, Embedded Finance, crypto, fraud and financial crime prevention, and more – all developed in collaboration with industry experts and leaders.
Current themes


No part of this site can be reproduced without explicit permission of The Paypers (v2.7).
Privacy Policy / Cookie Statement
Copyright