Wero – the future of pan-European A2A payment interoperability
Estera Sava
23 Oct 2026 / 8 Min Read
In an interview for The Paypers’ A2A Payments Report 2026, Ludovic Francesconi, Chief Member and Strategy Officer at EPI Company, shares how Wero is working toward pan-European A2A payments interoperability.
For readers who haven’t followed it closely, what problem is Wero solving, who’s behind it, and how does it fit into the European payments landscape? What’s the current country reach and usage?
Wero is a European payments solution, backed by 18 shareholders (banks and PSPs) who have supported us since our 2024 launch. Wero is live in Germany, Belgium, and France for peer-to-peer (P2P), and ecommerce in Germany and Belgium. It launched in Luxembourg in September 2026 and is migrating Payconiq to leverage its user base.
In October 2026, we will start migrating iDEAL in the Netherlands; co-branding happened already in early 2026. The next operational phase focuses on migrating merchants and is critical, as iDEAL is the preferred solution, accounting for over 70% of ecommerce transactions. Austria will follow and could enable Wero’s expansion to other European countries.
We focus on consumers, as a direct account-to-account (A2A) solution for all use cases: P2P, ecommerce, and point-of-sale (POS). Live in Belgium and Luxembourg, POS is planned for Germany and other markets and includes QR code functionality. By the end of 2027, it will feature contactless payments with near-field communication (NFC).
Our goal is a full omni-channel, all-in-one, pan-European payments solution. Live in multiple markets, Wero can address Europe’s payment fragmentation. Its scale can attract large players, acquirers, merchants, and surrounding local ecosystems, and is especially relevant for acquirers and merchants, who find implementing national solutions cumbersome. Wero requires only one integration, helping cover several markets simultaneously.
We have 60 mln users, and with iDEAL’s ~15 mln users, Wero will reach 75 mln and grow further. Transaction figures aren’t public, but we are happy with our P2P and ecommerce market momentum. For ecommerce, merchant appetite is strong. In Germany, we have onboarded ~4,000, including large enterprises (e.g., Lidl, Eventim, Decathlon, and DM) and international ones like Dott. France is next, where Veepee, Decathlon, E.Leclerc, Orange, Fnac Darty, and others want to offer Wero.
Which merchant use cases and verticals does Wero support today, and which are you actively building toward?
Wero for ecommerce includes single, immediate payments and refunds. It also offers pre-disputes, dispute management, and fraud detection, all essential to trust.
We will open subscriptions and subscription management so consumers can see and monitor merchants with active subscriptions in-app, starting in Germany in 2027, and Belgium, France, and other markets next. One-click, frictionless payments without SCA will follow – a particularly relevant development for in-app, in-store POS payments. Default capture for click-and-collect is also planned and important for merchants.
How does Wero handle disputes and chargebacks?
If transaction issues occur, consumers can use the Wero app to file claims: for fraud, if they believe a transaction is fraudulent; for technical issues, if an incident caused a failure or duplicate payments; or for commercial disputes, where the objective is to facilitate consumer-merchant communication.
As best practice, we first advise consumers to contact the merchant, particularly for issues it can solve directly (e.g., missing/damaged parcel). If it can’t, we facilitate the pre-dispute flow. In exceptional cases, we can settle chargebacks as cards do. We escalate with the bank, which prompts the merchant’s acquirer to settle it. But as most transactions are strongly authenticated, consumers will have difficulty claiming this. We do this in all markets, except the Netherlands. iDEAL doesn’t have dispute management, and we postponed it until migration finalises.
Each European market largely has its A2A scheme – Bancomat in Italy, Bizum in Spain, MB WAY in Portugal, Vipps MobilePay in the Nordics. How does the newly announced European Network for Payments (ENP) build on the MoU signed in February 2026, and what will it mean for a merchant working across markets?
For A2A interoperability, we have announced the creation of the new entity named ‘European Network for Payments (ENP)’ with Bizum, SIBS–MB WAY, Bancomat, and Vipps MobilePay. The network could extend to other European payment solutions over time, subject to the partners’ agreement and its technical and operational requirements.
Europe has no cross-border service for transactions between all countries. Although expansion is possible, we are building this interoperability hub in markets with well-established solutions.
Our objective is to enable, for example, a German user vacationing in Spain to pay with Wero using Bizum’s acceptance network – through a partnership where interoperable solutions communicate without building bilateral connections. We’re aligning scheme processes, technical setups, and rules. If issues occur, solutions must work flawlessly together so claims can be managed on both sides.
Interoperability will cover all use cases, but we are yet to decide whether it will have a new label or an umbrella brand. The core message is that users can pay with Wero wherever they see Bizum. Interoperability will also be transparent for merchants. They might need to sign a contract addendum (details still to be defined), but the bottom line is that if they accept Bizum, they can accept Wero.
Which value-added services do you plan to offer, and how do you see Wero evolving in the future?
Our roadmap is ambitious. Today, Wero is more of a P2P and ecommerce payment method, used with a button. For POS, you also need a wallet; this is our priority. The app is live in Germany, France, and Luxembourg (where all banks have adopted it), and is planned for Belgium, with new services (cards, NFC integration) and contactless payments via NFC.
We will also offer value-added services, starting with loyalty. What’s challenging with contactless payments is that users choose a default wallet. To reach our objective, Wero needs to be their preferred method. This requires additional services (loyalty, tickets, boarding passes, etc.) and work on digital identity, which is our next focus. This is the 2027/2028 roadmap and the key to the Wero app’s future adoption.
This editorial piece was first published in The Paypers' Account-to-Account Payments Report 2026, which features insights into global trends, technologies, partnerships, and the next phase of the A2A evolution. Access the full report to understand where the A2A payments ecosystem stands today and what’s next.
About the author
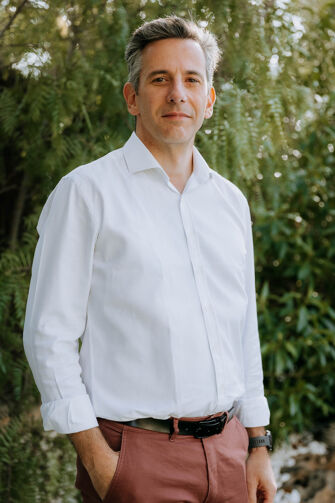
Ludovic Francesconi is Chief Member & Strategy Officer at EPI Company, leading member relationship and development, as well as geo-expansion, market intelligence, and strategy efforts. He has been supporting the European Payments Initiative since January 2021, aiming to build an independent European solution and connect Europe’s payment industry.
About EPI Company
EPI (or European Payments Initiative) is a European-led consortium founded by 16 European banks and PSPs, committed to delivering a unified mobile payment service to all European companies and citizens through the Wero wallet. EPI intends to enable European consumers to carry out all types of retail transactions easily, via a resolutely sovereign digital wallet, based on an instant payment framework (SCT standard), A2A methodology, and covering all payment use cases. Access our websites here – EPI and Wero.
News on Payments
Interviews on Payments
The Paypers is a global hub for market insights, real-time news, expert interviews, and in-depth analyses and resources across payments, fintech, and the digital economy. We deliver reports, webinars, and commentary on key topics, including regulation, real-time payments, cross-border payments and ecommerce, digital identity, payment innovation and infrastructure, Open Banking, Embedded Finance, crypto, fraud and financial crime prevention, and more – all developed in collaboration with industry experts and leaders.
Current themes


No part of this site can be reproduced without explicit permission of The Paypers (v2.7).
Privacy Policy / Cookie Statement
Copyright